01 Start with the cost question your project actually needs to answer
There is no single price for setting up a factory in China. Electronics assembly, machining, food production and chemical processes can require very different equipment, clean environments, utilities, treatment facilities and validation, even in buildings of the same size. The useful question is: for this product, capacity, process and operating specification, how much cash must be paid, and when?
This guide is for investors establishing their own manufacturing plant in China. It covers early budgets for leased factories, industrial land and new construction, and the conversion of existing facilities. Contract-manufacturing purchases are not investment in your own factory, and company registration fees are only a small part of a complete setup budget. Prepare a project brief before requesting quotations from suitable properties and suppliers.
Produce three connected views: a uses-of-funds budget showing what money buys; a monthly cash forecast showing payment dates and shortfalls; and a steady-state operating model showing cost per saleable unit. Each should trace back to the same scope. Do not count an equipment payment as both an investment item and an additional cash-flow expense.
02 Separate investment, registered capital, expenses and funding
Registered capital is the shareholders’ subscribed capital commitment. It is not a government factory setup fee and does not automatically equal total project investment. Newly established limited liability companies generally need to arrange contribution deadlines under the Company Law; incorporation date and any special provisions affect the precise application. Paid-in capital may lawfully support business operations, but its availability must match contractual payment dates. [S04]
| Concept | How to use it in the budget | Common error |
|---|---|---|
| Fixed assets and construction | Specify equipment, buildings and installation by scope | Treating every asset payment as an immediate income-statement expense |
| Startup and ramp-up expenditure | Recruitment, training, commissioning, trials and early support | Capitalising every startup payment without accounting review |
| Working capital | Inventory, receivables, payables and operating cash commitments | Treating an invoiced sale as cash already collected |
| Deposits and refundable security | Include cash outflows and identify recovery conditions | Ignoring cash tied up or assuming full recovery |
| Capital, shareholder loans and bank borrowing | Record as funding sources | Adding funding sources to investment uses and double-counting |
| Contingency and cash buffer | Cover estimate uncertainty and liquidity separately | Reserving the full same delay risk in several places |
The budget supports a business decision. Accounting recognition, tax deductions and capitalisation require separate professional assessment. The investment committee needs to understand committed expenditure, peak funding pressure, recoverable payments and the conditions for releasing further money.
03 Confirm the inputs before requesting prices
Use one consistent brief covering product specifications and certification markets, initial and future capacity, shifts, process flow, make-or-buy boundaries, equipment, floor area and loads, utility demand, emissions and hazardous materials, and the target operating date. Convert annual volume into cycle times, yield, equipment utilisation and effective working hours before estimating machines and staffing.
For example, producing one million units on one shift or two shifts can change equipment quantities, building area, overtime, maintenance windows and night-time logistics. Comparing two parks using different shift assumptions confuses production-design differences with location prices. Whenever capacity or process changes, revisit power, environmental facilities, fire safety, logistics and funding together.
Maintain an assumption register with value, unit, source, owner, confirmation date and reliability. Distinguish formal quotations, design estimates, benchmarks and unresolved inputs. An all-in price per square metre without quantities may help initial screening, but it is insufficient for an investment approval or construction contract.
04 Choose a facility route and compare the full delivered scope
| Route | Main cash items | Priority checks | Frequently omitted |
|---|---|---|---|
| Lease a ready-built factory | Deposit, prepaid rent, fit-out, installation and reinstatement | Permitted use, title, existing fire provisions, loads and capacity | End-of-lease reinstatement, rent-free conditions and utility upgrades |
| Acquire land and build | Land-related payments, design, construction and external connections | Planning, site handover and land-supply obligations | Site preparation, ground conditions, external lines and construction-period finance |
| Buy an existing factory | Purchase, transaction costs, repairs and equipment interfaces | Encumbrances, previous use and applicable procedures | Concealed works, environmental history and unsuitable use |
| Commission a customised building | Customisation payments, lease or purchase terms and process fit-out | Handover standard, delay responsibility and installation access | Design variations and the gap between handover and operating readiness |
Assess industrial land prices together with location, use, tenure, handover conditions and contractual obligations. National industrial land policies allow different supply arrangements, but availability for a particular plot depends on the local plan and contract. A quoted minimum elsewhere is not a price available throughout China. [S14][S18]
A leased building can still require project procedures and substantial engineering. A ready-built factory reduces construction work only when the process, property and applicable requirements fit. Compare both options at the point where they can support your production requirements, rather than comparing bare rent against a fully fitted new building.
05 Break one-time investment into packages suppliers can quote
| Work package | Minimum scope | Questions for the quotation |
|---|---|---|
| Premises and preparation | Deposits or land, surveys, investigations, design and due diligence | Refundability, tax basis and validity |
| Building and alterations | Partitions, floors, strengthening, lifting openings and roofing | Quantities, concealed works and reinstatement |
| Utilities | Transformers, power distribution, gas, water, steam, compressed air and drainage | Inside/outside boundary, capacity and connection date |
| Production systems | Machines, tooling, moulds, robots and software interfaces | Accessories, transport, installation, trials and acceptance |
| Environment and safety | Collection and treatment, hazardous-waste storage, safeguards and fire alterations | Consistency with the process and recurring consumables |
| Quality and information | Instruments, calibration, traceability, networks and implementation | Users, licence period and maintenance renewals |
| Startup and readiness | Recruitment, training, commissioning materials, validation and testing | External services versus internal staff responsibilities |
Do not reduce facility compliance to a single “approval fee”. Costs may include technical investigations, reports, design, construction, testing, corrections and ongoing operation. Identify environmental assessment, discharge permitting, energy and carbon assessment, safety and occupational-health requirements according to the project. Do not add inapplicable items mechanically or assume paying a consultant replaces the required facilities and conditions. [S08][S09][S11][S12][S13]
Assign one accountable owner to each package. Document where the power contractor’s work ends, which flange or connection the machine supplier covers, and who installs exhaust collection. An interface excluded by both contractors will become additional investment unless resolved before ordering.
06 Include delivery, commissioning and production ramp-up in equipment cost
Compare equipment beyond the ex-works price: transport, insurance, applicable import taxes, installation, foundations, power and gas connections, software, spares, training, commissioning and acceptance. Use consistent currencies and delivery terms. Confirm the importer, classification, origin, regulatory conditions and applicable rates rather than applying one generic customs percentage.
For relocated used equipment, verify import requirements, remaining life, maintenance support, technical records and modification needs. Used mechanical and electrical products are subject to specific regulatory requirements; a low purchase price does not establish that a machine can be imported and installed on time. [S17]
Connect payments to evidence for design approval, factory testing, shipment, installation, performance testing and stable production. Acceptance criteria should cover cycle time, yield, energy consumption, safety and continuous running with the actual materials and specifications, rather than an unloaded demonstration. Have contract specialists establish correction and warranty provisions.
Budget for producing good units during the ramp. Trial materials, scrap, rework, low-load operation and supplier support may continue consuming cash after equipment is delivered. Put these costs in the ramp-up plan instead of assuming stable output in the delivery month.
07 Build operating costs from people, loads and shipment patterns
Labour costs include more than advertised base salaries. Build staffing by role and include applicable social insurance and housing fund contributions, overtime or shift arrangements, recruitment, training, benefits, accommodation or transport, and replacement hiring. A local minimum wage is a legal floor, not a recruitment price for skilled operators, engineers or quality staff. This guide does not assume one nationwide labour rate.
For electricity, distinguish connected equipment load, operating demand, hours, power factor and the applicable charging structure. Ask the property and utility provider to confirm capacity, expansion cost, payer and availability date. A nominal connection does not automatically mean that the tenant can use all that capacity. Do not rely on an oral electricity-price claim.
Calculate logistics on comparable shipment units: inbound materials, outbound goods, port or airport handling, warehousing, packaging, customs services and exceptions. Shorter distance does not always mean lower total cost. Frequency, lead-time variation, minimum shipment size and customer delivery windows also affect inventory and transport.
Divide steady-state costs by saleable good output, not theoretical capacity. Separate fixed, variable and step costs. Adding a shift, warehouse or transformer may create a discrete cost increase; a straight-line extrapolation can conceal it.
08 Keep tax economics, cash payments and incentives separate
Quotations should state whether tax is included, the invoice type and issuer, tax amount and payment timing. Maintain both an economic-cost view and a cash-payment view when needed. Eligibility for input VAT deduction, and the timing of deduction or refund, depend on taxpayer status, use, documentation and applicable rules. The VAT Law effective from 2026 and its supporting policies do not mean that equipment VAT is always immediately recoverable in cash. [S19][S20]
Imported equipment, technical services and related-party settlements can raise distinct tax and foreign-exchange questions. Resolve them before finalising contracts and funding. Do not assume every foreign-invested enterprise qualifies for a particular income-tax preference or include unconfirmed treatment in the base profit model.
Record policy support as a conditional scenario: implementing body, written basis, eligibility, performance conditions, application window, expected payment and potential repayment obligations. Incorporate only sufficiently substantiated arrangements into cash planning with prudent timing. Investment-promotion statements are not cash receivables.
The base case should show whether the project remains affordable without the proposed incentive. If liquidity depends on every award arriving on schedule, the investment committee should see that dependency explicitly.
09 Find working-capital and funding pressure in a monthly model
An initial working-capital estimate can start with raw materials, work in progress, finished goods and receivables, less reasonable trade payables and customer advances. But material prepayments, equipment advances and minimum cash reserves also tie up funding. Inventory plus receivables minus payables does not capture the entire factory setup requirement.
Schedule customer collections, capital contributions, borrowing, equipment and construction payments, payroll, rent, taxes and material purchases by month. Closing cash equals opening cash plus receipts minus payments. Find the lowest balance through construction and ramp-up; the additional funding needed to maintain the minimum cash balance is the timing gap to solve.
| Model check | Question to answer |
|---|---|
| First collection | After customer qualification, production approval and payment terms, when does cash arrive? |
| Opening inventory | Do minimum order quantities and sea freight create purchases above normal monthly consumption? |
| Construction payments | Do several contract milestones fall in the same month? |
| Tax cash tied up | Is payment earlier than a possible deduction or refund? |
| Available finance | Is the facility approved, and when are drawdown conditions met? |
Treating unapproved loans as certain receipts creates a false cash cushion. Identify committed, conditional and unarranged funding and match availability to payment needs. The Excel workbook provides both investment details and a monthly cash schedule. The total planning envelope and the funding shortfall are different outputs.
10 Worked example: a leased 1,000-square-metre assembly factory
Every number below is a teaching assumption, not a market quotation for a city, park or supplier. Assume a 1,000-square-metre leased building with basic provisions suitable for assembly without special processes. All amounts are CNY 10,000. An actual project requires its own process and site assessment.
| Use of funds | Assumed amount | Basis |
|---|---|---|
| Deposits and prepaid premises charges | 18 | Cash tied up; avoid double-counting rent covering the same period |
| Building fit-out | 120 | Defined construction scope |
| Equipment and tooling | 240 | Includes the transport and installation assumed in this example |
| Utility connections and production support | 45 | Excludes work already in fit-out or equipment |
| Design, testing and external services | 18 | Defined assumed service scope |
| Recruitment, training and net trial expenditure | 24 | Excludes inventory included below |
| Initial working capital | 100 | Net operating funds, excluding minimum cash reserve |
| Minimum cash reserve | 40 | Separate liquidity buffer |
One-time investment totals 465. A 10% illustrative contingency applies only to fit-out, equipment and support packages totalling 405, giving 40.5. Adding working capital and the minimum cash reserve produces a simplified funding envelope of 645.5, or CNY 6.455 million. The 10% input is not an industry standard.
If production is delayed by two months and each month adds 25 of net fixed cash expenditure not already covered by ramp-up or contingency, the stress case adds 50 and reaches 695.5, or CNY 6.955 million. Adjust existing provisions covering the same risk rather than adding it twice. This total-only example does not establish a payment and collection schedule, so 645.5 is not an actual peak financing gap. The downloadable workbook adds a separate illustrative 18-month schedule to demonstrate that distinction.
11 Follow eight budgeting steps with clear responsibility
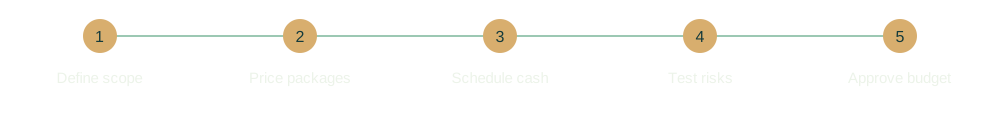
| Step | Action | Accountable team | Output and next-step condition |
|---|---|---|---|
| 1 Define scope | Fix products, process, initial capacity and facility route | Sponsor and process lead | Approved brief with owners for unresolved assumptions |
| 2 Build packages | Separate construction, equipment, utilities, startup and working capital | Engineering, procurement and finance | Every interface covered once |
| 3 Obtain evidence | Request comparable property and supplier quotations | Procurement and local coordinator | Date, scope, tax and lead time documented |
| 4 Verify conditions | Assess site, applicable procedures and facility scope | Engineering and relevant specialists | Major gaps included in corrective plans and cost |
| 5 Schedule cash | Map payments, receipts and funding by month | Finance and project manager | Lowest cash balance explained |
| 6 Test stress cases | Vary timing, exchange rates, output, yield and collection | Finance and operations | Base, downside and staged-investment options |
| 7 Approve baseline | Approve amount, scope, reserves and authority | Investment decision-makers | Version and change triggers recorded |
| 8 Update forecast | Track commitments, payments and remaining expenditure | Project manager and finance | Forecast-to-complete and funding gap remain visible |
Workstreams can overlap, but immature process estimates should not be presented as a fixed total price. Screening budgets compare routes; design budgets support site and investment decisions; contract budgets control execution. Each stage should add real quotations and quantities, not simply more formatting.
12 Identify the variables that change the decision
Test equipment prices and foreign exchange, opening delays, slower volume ramp-up, lower yield and late customer collections. Vary individual drivers first, then build internally consistent combined scenarios. A delay normally affects hiring, rent, inventory and receipts; adding rent while leaving the original revenue dates unchanged understates the effect.
Distinguish fixed-price contracted amounts from unpriced packages. Do not apply the same escalation to everything. Relate contingency to identifiable risks such as uncertain quantities, ground conditions, old-building alterations, equipment interfaces or commissioning failure. Missing base scope belongs in the base budget, not hidden inside contingency.
If a machine can be purchased in phase two, compare the effect on cash, unit cost, delivery and capacity. Phasing can also add repeat construction, shutdowns or revalidation. It is a trade-off, not automatic savings.
13 Retain evidence for quotations and budget changes
Compare scope exclusions, warranties, retention, payment percentages, delivery, taxes, currency and variation pricing as well as headline prices. Flag expired quotations and quotations based on superseded drawings. An unwritten discount is not a confirmed saving.
After approval, track paid amounts, unpaid contractual commitments and forecast expenditure required to finish the remaining scope. Low payments to date may simply mean that final instalments are concentrated later. Changes in the estimate at completion should trace to quantity, unit price, scope, timing or risk.
A change request should explain why the change is needed, what it affects, cost, delay and approval authority. When design, process, equipment, utilities or treatment facilities change, verify procedural and technical interfaces before authorising procurement. Use hold points where necessary rather than building first and seeking budget approval afterwards.
14 Questions to resolve before committing investment
Should registered capital be as low as possible?
It should fit operating needs, funding arrangements, shareholder obligations and contractual requirements. A small number does not solve the payment peak when equipment arrives. Finance and legal advisers should assess the capital and financing structure for the actual project. [S04]
Is leasing a ready-built factory always cheaper than building?
No. Initial cash requirements differ, but specialised alterations, utility upgrades, lease length, reinstatement and expansion limits can change lifetime cost. First establish that both routes are feasible, then compare the same capacity and operating period.
Can incentives cover an early funding shortfall?
Only after eligibility, amount, conditions and payment timing have reliable support can that possibility be assessed prudently. Keep unconfirmed support in conditional scenarios rather than making the base plan depend on it.
What information produces a decision-useful budget?
Provide the process flow, equipment and utility lists, initial capacity, facility requirements, target regions and schedule. Site checks and comparable quotations should produce investment uses, cash flow, risks and implementation phases, not just one total.
15 Connect costs to site selection and the factory setup process
Budgeting tests affordability; site selection tests production and operating feasibility; the setup process establishes execution order. A new property changes fit-out and interface costs. A new process or capacity changes site and procedural requirements. A new funding arrangement may change project timing.
Yipu Consulting can help organise requirements, contact candidate industrial parks and properties, coordinate quotation inputs and prepare comparisons. Relevant specialists handle engineering cost, design, tax, legal and banking matters. For the first discussion, share your existing documents and the three cost items with the most uncertainty so the next investigation has a clear purpose.
Download the complete Excel workbook
China factory budget and funding plan
Six worksheets covering an investment overview, 23 investment packages, an 18-month cash schedule, 36 preparation checks, supplier quotation comparison and 12 investment risks.
Download Excel workbook (.xlsx)Yellow fields are editable. The workbook includes instructions, formulas and evidence requirements. Budget amounts are clearly marked teaching assumptions, not supplier quotations. Replace them with supported project inputs before making a decision.
Official sources and references
Prepared 18 September 2026. References support the associated regulatory statements. Checklists, weights, schedules and monetary examples are project-management guidance, not official prices or rankings.
- S04 · Company Law of the People's Republic of China
- S08 · Construction Project Environmental Impact Assessment Classification Catalogue
- S09 · Pollutant Discharge Permit Regulations
- S11 · Fixed-Asset Investment Energy Conservation Review and Carbon Emissions Assessment Measures
- S12 · Construction Project Safety Facilities: simultaneous design, construction and use
- S13 · Construction Project Occupational Disease Protection Facilities: simultaneous design, construction and use
- S14 · Industrial land supply policy
- S17 · Regulatory requirements for imported used mechanical and electrical products
- S18 · Industrial Project Land Use Control Indicators (Ministry of Natural Resources, 2023)
- S19 · Value Added Tax Law of the People’s Republic of China (effective 1 January 2026)
- S20 · Announcement on input VAT deductions and related matters (2026, No. 13)